I was at a wonderful MegaCorp reunion a few nights ago and a few colleagues were celebrating their first year of retirement, or were planning to at the end of the year. A couple friends said that despite a lot of planning, they weren’t entirely confident that their financials were going to hold up to the next few decades of retirement life.
Despite having financial advisors and having done Monte Carlo analyses with tools like FIREcalc.com, many people are still nervous. According to research, about 70% of people worry if their savings are going to hold out.
My initial reaction is that they shouldn’t worry so much. Especially people retiring from good jobs with a healthy nest egg. Our portfolio is actually much bigger than what we retired with – despite a whole decade of retirement spending behind us. (The S&P returned a healthy +11.9% annually above inflation over the last 10 years).
I would find it hard to believe that our nest egg will swing to the negative in the next 10 years, but a recent study from the Employee Benefit Research Institute, shows that many retirees are in exactly that situation.
As the chart below shows, the share of people with “LESS” money than half of what they started with (in purple) is higher than the people with “ALL” or more assets left (in orange). The discrepancy is especially for sharp for households that started with less than $200K in savings.
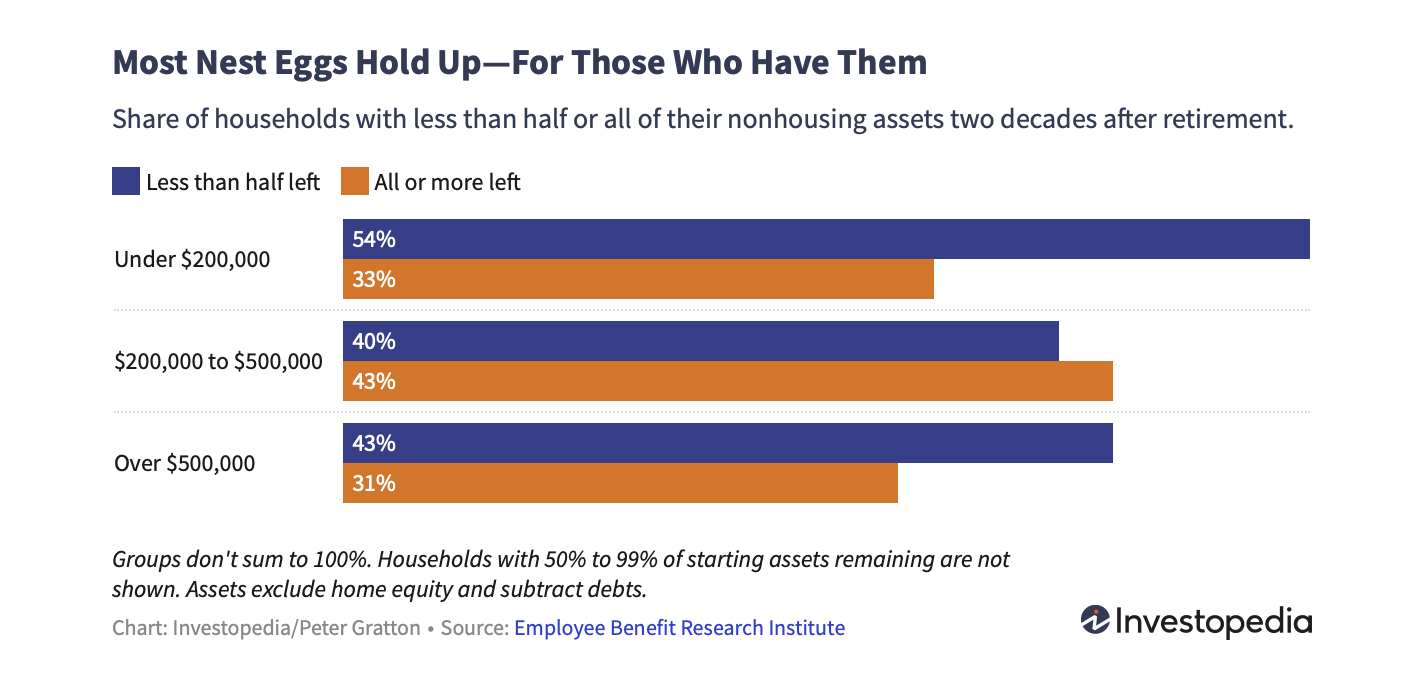
And, keep in mind that this chart starts in an optimistic place. It only includes people that have ANY savings at retirement. About 30% of American households retire WITHOUT any savings and rely almost exclusively on Social Security. Those people are truly at the mercy of the inflation / Social Security COLA cycle each year.
How long have you been retired and how are your retirement savings holding up?
Image: Pixabay

